quantitative analyst recruitment agency and headhunters
your next quant, chosen by a headhunter who can read a pricing model.
We combine our data, our sector experts and our AI algorithms to identify the headhunter most relevant to your role, from the first junior quant to a senior model validator.
- no setup fees, pay on hire
- guaranteed replacement
- a hire signed in under 26 days
they hire their quants with muzzo
how do you hire a quantitative analyst through a recruitment agency?
A quantitative analyst builds the models that price a derivative or measure market risk. Muzzo gives your role to the headhunters who place the most quants: they verify the code and models already delivered in production. Fee of 5 to 30%, paid on hire. Leaves within 3 months: we restart the search free.
how it works
you only pay if you hire
01
you describe the role
Using the form above: the role, your company, your desk or your market. The rest is scoped in your first conversation with the Muzzo team.
02
our data chooses the headhunters
Our AI picks those who have hired the most quants, from more than 2,500 selected headhunters.
03
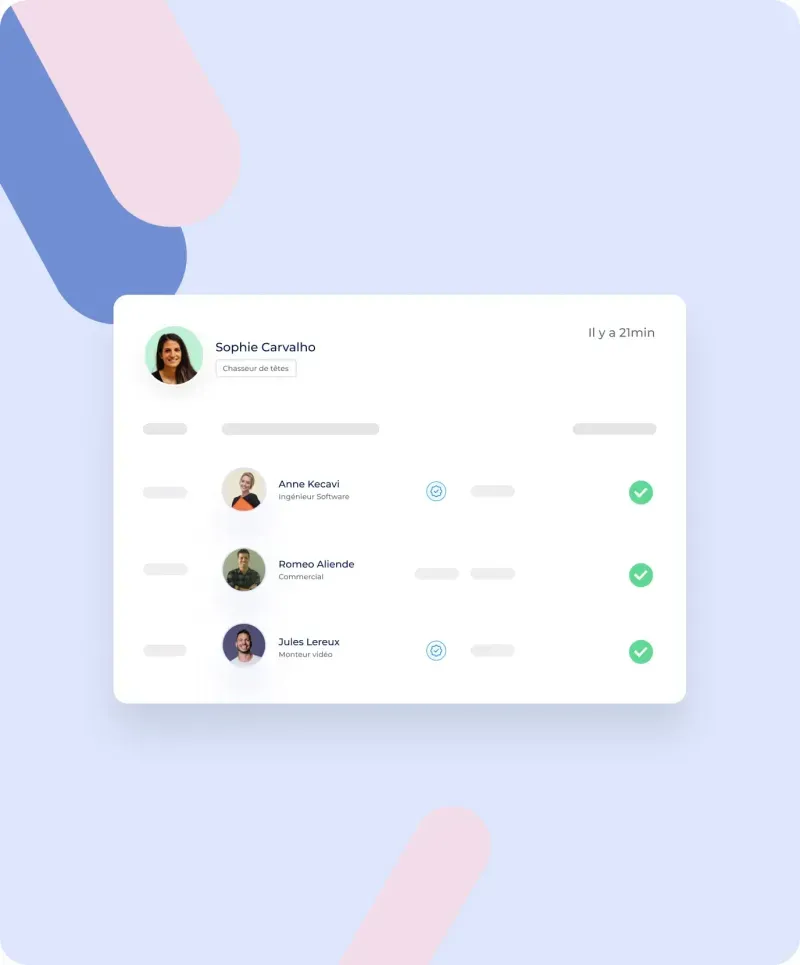
you meet the best profiles
Approached and qualified by headhunters who are quantitative finance experts. You choose who you meet.
04
you hire, then you pay
Not before. If your new hire leaves within 3 months, we restart the search at no cost.
they hired with muzzo
Muzzo's strength is the diversity of its recruiters: there is always someone listening to our needs.
With Muzzo, I get the reactivity of a marketplace and the quality of a search firm.
let's talk about your hire
Antoine and the Muzzo team help you scope your role and choose the right headhunters. Describe your role in the form: we'll call you back to discuss it.
Antoine GigomasCEO and co-founder of Muzzo
one last question?
With Muzzo, you set the fee, between 5 and 30%, and you only pay it on hire: no deposit, no fixed fees. A junior quant and a senior model validator in investment banking don't take the same search. The fee follows that difficulty, and the Muzzo team helps you set it.
You have a double guarantee. If your new hire leaves within 3 months, for example because the desk didn't match what was planned, we restart the search at no cost. If no replacement is found within 4 months, we refund 50% of the fees. On average, 94% of Muzzo hires are still in post after 3 months.
headhunters who specialise in quantitative finance are ready to start
A hire signed in under 26 days. You only pay when you hire.
the reality
a quant is judged on their models, not their degree
a good degree isn't enough to judge a model
Many profiles come from the same engineering schools or applied maths programmes. The headhunter asks what the candidate has actually delivered in production, not just what they studied.
pricing, risk and trading are three different jobs
A pricing quant structures a derivative product, a risk quant validates regulatory models, a trading quant codes algorithmic strategies. The headhunter starts from your desk, not the job title.
a hiring mistake costs a model that has to be rebuilt
A poorly handed over or poorly documented model exposes the bank or fund to internal audit. The headhunter verifies the deliverables, the programming language and the validation methods before introducing anyone.
the roles
the quant profiles our headhunters go after for you
From the first line of code to the trading desk, each role goes to a headhunter who has already hired that profile.
junior quantitative analyst
They code and test model components under the supervision of a senior quant. Often the first role after an engineering school or a master's in applied mathematics.
pricing quant
They build the models that value a derivative or structured product, on a trading floor or at a financial software vendor.
market risk quant
They measure a portfolio's exposure and feed the regulatory risk models, working with internal control teams.
trading quant and algorithmic strategies
They develop and monitor automated trading strategies, a role that demands as much rigour on the code as on the markets.
model validator (model validation)
They replay and challenge models built by other teams, an internal audit role specific to banks and large asset managers.
quantitative data scientist in finance
They apply machine learning methods to market data, at a hedge fund or fintech, on the border between quant and data science.
the method
a headhunter who specialises in quantitative finance, not an agency that does everything
The quant title covers different jobs. So the method starts from what the role must produce.
we define the desk and the scope
Pricing, market risk, algorithmic trading or model validation: the brief describes the expected deliverables and the programming language used, not just the title.
a headhunter who places quants
From more than 2,500 selected headhunters, your role goes to those who place the most quants in investment banking, asset management and fintech.
models and code verified
The headhunter asks for examples of models delivered, the language used, Python, C++ or R, and cross-checks them before introducing anyone.
the figures
a quantitative analyst's salary in figures
€67k
median gross annual pay for banking operations and financial markets managers over 45 (between €44k and €114k), against €53k under 351
€64k
median pay in companies with 250 or more employees (between €43k and €92k), against €55k in smaller companies1
23,917
direct jobs in French asset management companies at the end of 2023, up 8.6% year on year2
hiring a quantitative analyst: what you need to know
The quant profession combines advanced mathematics, programming and a good reading of financial markets. A prestigious degree doesn't guarantee a candidate can deliver a model that is usable in production, documented and robust to edge cases.
A headhunter who specialises in quantitative finance asks for concrete examples of models delivered and verifies the programming language actually mastered, beyond the CV.
A pricing quant structures the valuation of a derivative product, a risk quant validates models for the regulator, a trading quant codes strategies that run live on the markets. The base skills overlap, but the deliverables and the pressure level are not the same.
Specify in the brief which desk is involved and the type of product tracked, rates, equities, credit or commodities. A rates pricing quant doesn't automatically transfer to an equities desk.
Quants work in investment banks, at asset managers, in hedge funds and increasingly at fintechs building their own pricing or scoring tools. Each environment expects a different level of regulatory rigour.
A quant from a large bank is used to strict documentation and model audit. A hedge fund quant is often more autonomous and closer to the direct result of their models. The headhunter checks which one fits your organisation.
A quant's pay combines a base salary and, depending on the organisation, a variable component linked to the desk or fund's performance. Experienced profiles also look at access to data and computing power before the salary on offer.
Experienced quants in complex product pricing or algorithmic trading remain rare: prepare an aligned offer from the brief, the market moves in days, not weeks.
The line between classical quant and financial data scientist is narrowing, with both working with market data to build predictive models. The difference lies mainly in the mathematical and regulatory rigour required on the quant side.
Machine learning is now part of market anomaly detection and algorithmic trading, alongside classical stochastic models. The headhunter checks how much of your role falls into one camp or the other before starting the search.
your questions about hiring a quantitative analyst
According to Apec, banking operations and financial markets managers, including quants, have a median salary that climbs to €67k after 45, against €53k under 35, on a range between €44k and €114k (2025 edition).
Yes. According to Apec, these jobs pay a median of €64k in companies with 250 or more employees, against €55k in smaller organisations, a gap worth anticipating if you're hiring at a fintech or a small hedge fund.
The quant prices and measures market risk in banking or asset management, over short horizons and on derivative products. The actuary prices and provisions an insurance risk over a contract's duration. For the second profile, see our actuary page.
Yes. According to the AMF, French portfolio management companies employed 23,917 staff at the end of 2023, up 8.6% year on year, a trend that is also driving demand for quantitative profiles at asset managers and fintechs, in addition to banks.
by Antoine Gigomas, CEO and co-founder of Muzzo ·